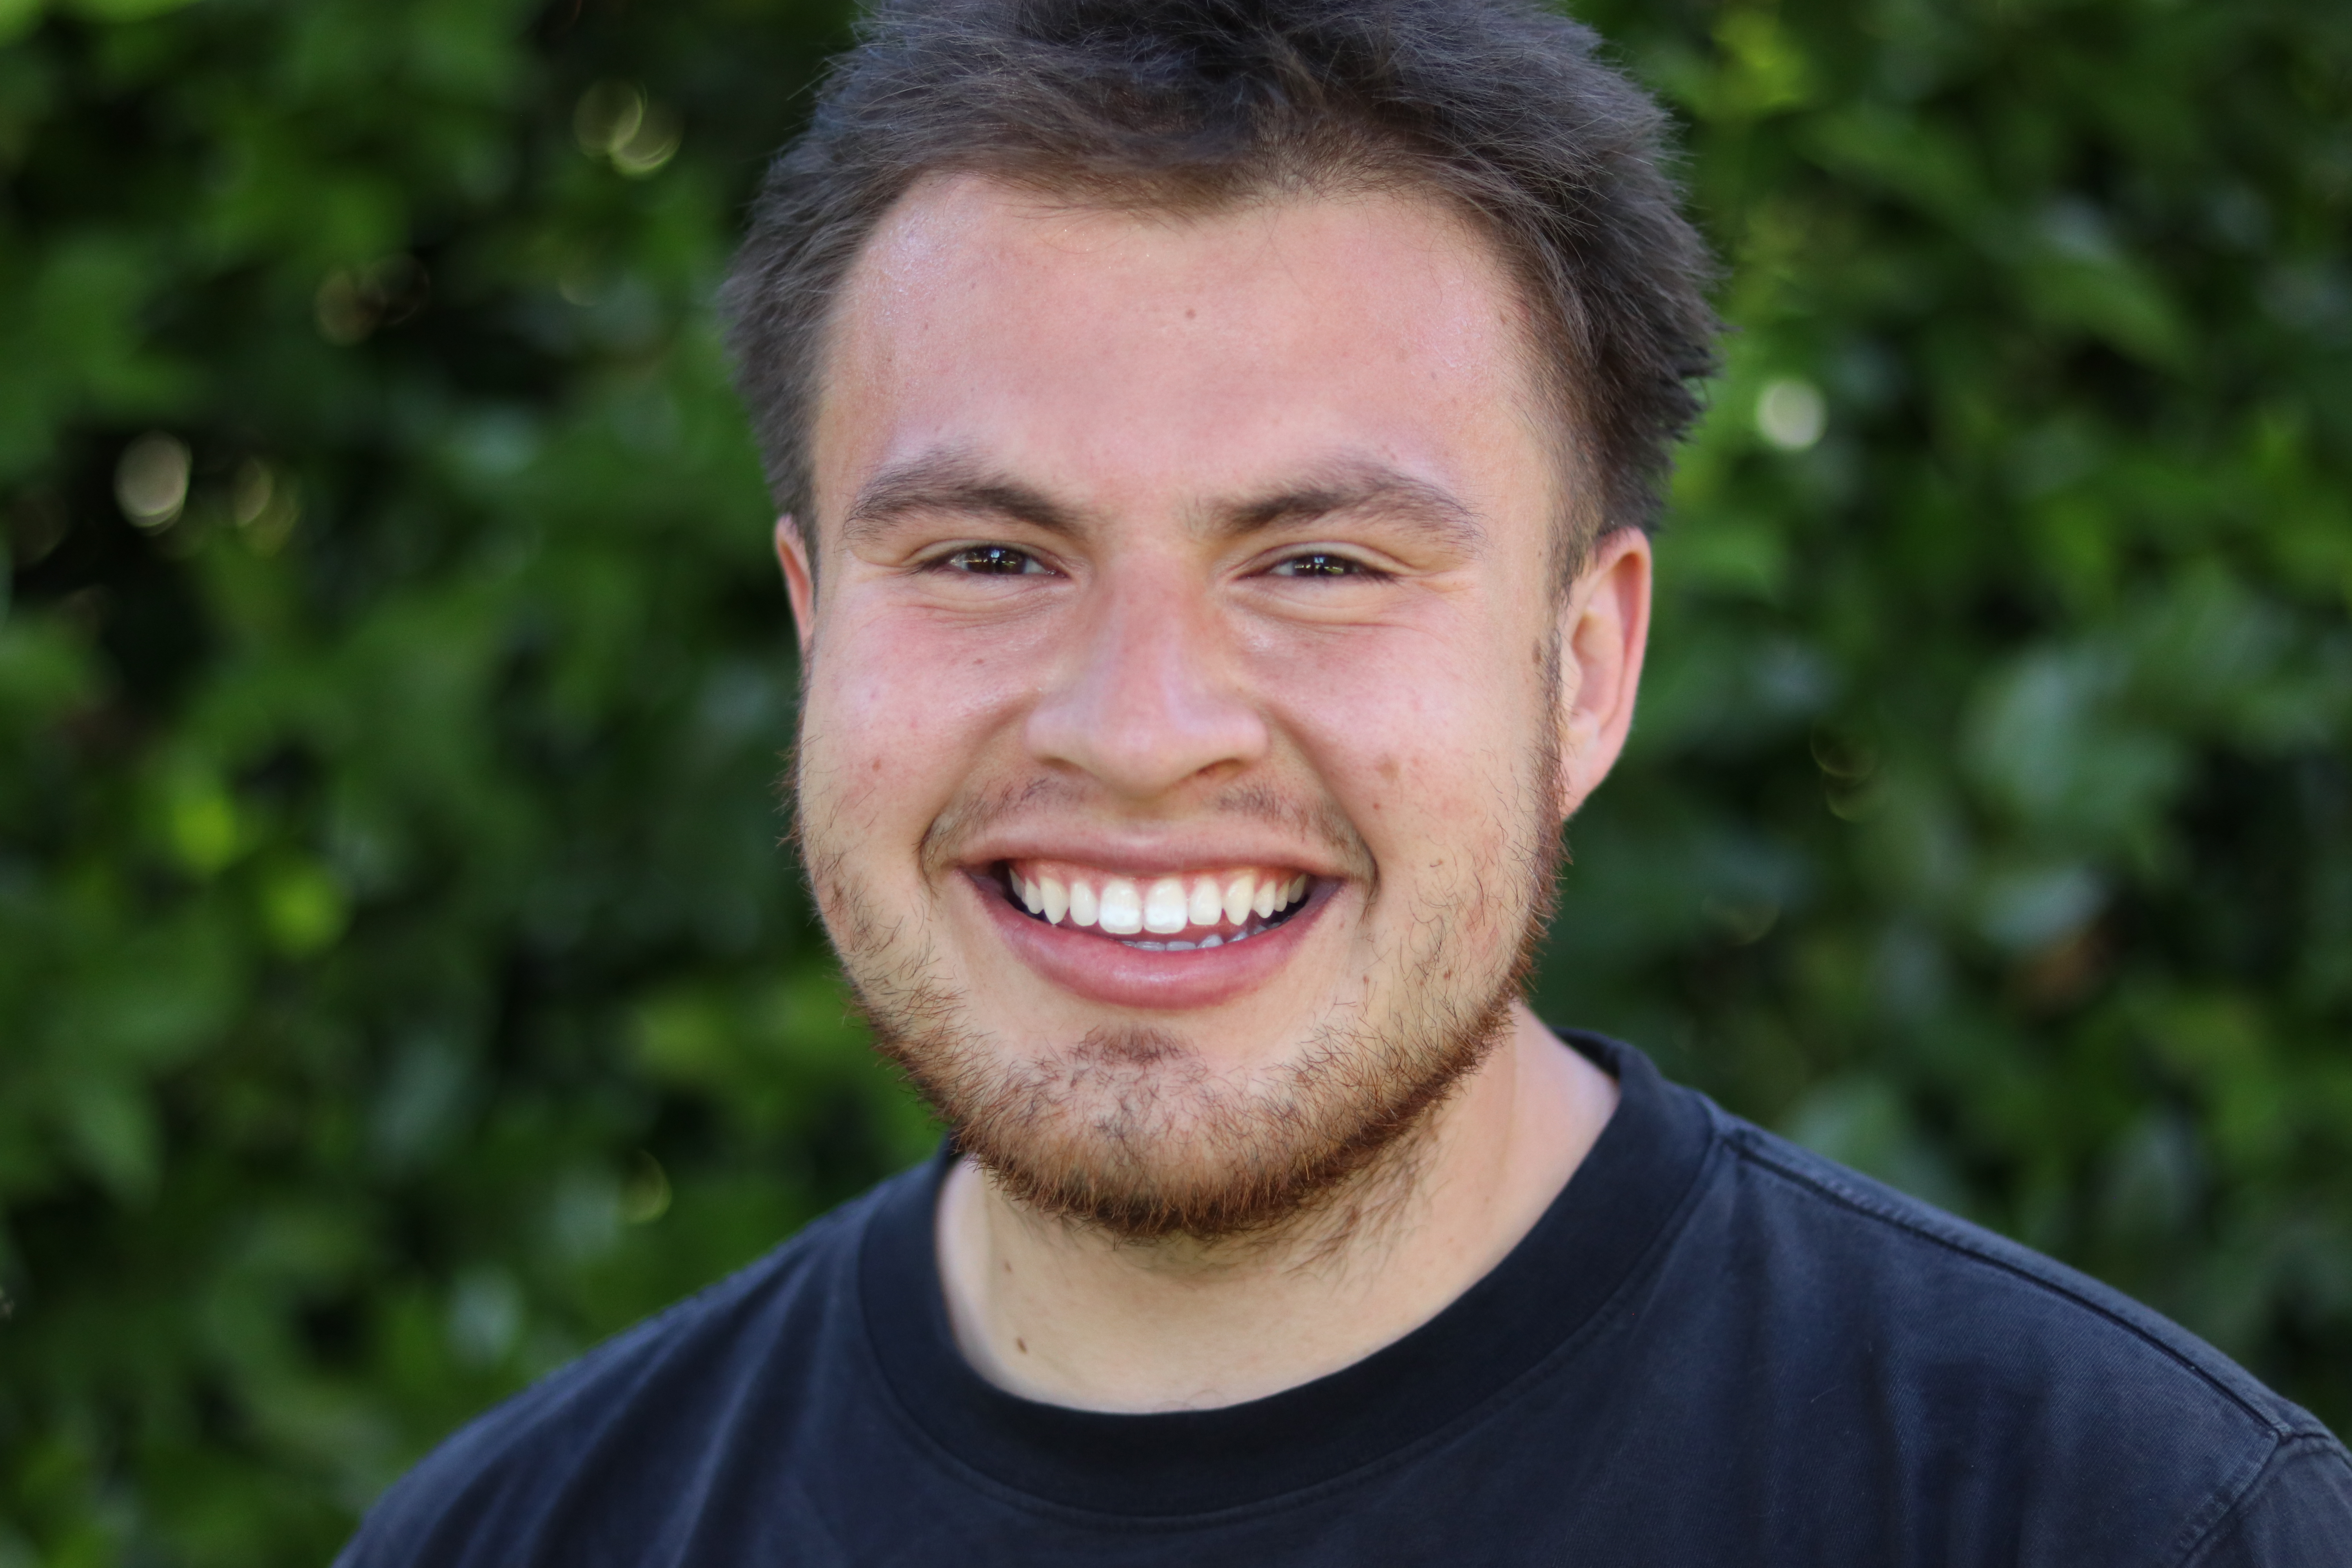
Christopher Lopez

Christopher Lopez

Economics  |  Research & Data Analysis

After earning my Economics degree from CSUN and working in institutional wealth management, I founded Explo Holdings to pursue equity research, portfolio management, and real estate development. I am preparing for graduate studies in economics with a long-term focus on economic consulting and policy research. In my free time I enjoy playing poker, enough to call it a hobby, but not enough to call me a degenerate (hopefully).

Current Work

Explo Holdings

Explo Holdings is a family investment and real estate holding company I founded in 2026. My work there is mostly research and bookkeeping: building and maintaining the financial database described below, writing due-diligence reports on public companies, and keeping unit-level accounting reconciled against bank and brokerage records. It also holds a residential construction project in Lancaster, CA.

exploholdings.com

Research Platform

Finance Terminal

A quantitative research platform I built in Python, SQL (DuckDB) and Streamlit. It covers 9,000+ U.S.-listed companies and ADRs over 30 years, joining daily prices, quarterly financial statements, FX rates, analyst estimates and insider trades, and runs a screening model that flags companies worth a deeper look.

Python Streamlit DuckDB Plotly SQL ThreadPoolExecutor
9,000+
Companies Covered
30 yr
Historical Data
~20M
Daily Price Observations
26
Linked Tables

Smart Screener

The screening model scores every company in the database across four factors. Hard gates filter out companies that fail basic quality thresholds before scoring begins, and the model was tested with a 20-year historical backtest. Its output is a ranked list that feeds into deeper due-diligence research.

30 pts
Valuation
25 pts
Quality
25 pts
Growth
20 pts
Momentum

Architecture

The platform has a Streamlit frontend, a SQL computation layer running inside DuckDB, and a local database holding tens of millions of rows of prices and financial metrics. Data is sourced from the Financial Modeling Prep API and refreshed daily.

26 linked tables covering prices, financial statements, FX rates, valuation metrics, analyst estimates, and insider transactions
Automated daily pipeline refreshes prices, financials, recomputes all metrics, and rescores the universe
Data quality audit that found and corrected currency mismatches in foreign-issuer financials, valuation ratios distorted by ADR share ratios, and 121 industry misclassifications
Rolling position backtester with fair value exit, fundamental stop-loss, and subperiod robustness testing

Professional Experience

Vance Wealth

Investment Associate  |  March 2025 – November 2025

At Vance Wealth, a registered investment advisory firm, I worked across the full scope of portfolio management operations for a book of approximately $700 million in client assets. The role combined daily trading execution with quantitative research and process automation, giving me hands-on experience with institutional-grade investment workflows.

Quantitative Research

Designed a direct indexing exclusion model that ranked S&P 500 companies on leverage and distress risk (Debt/EBITDA, Debt/Market Cap, Altman Z-score) and backtested 99 exclusion thresholds over ten years; the selected threshold outperformed by 72 basis points a year on average, in nine of ten years. The study found that highly leveraged firms outperform in rate-hiking cycles and underperform in rate-cutting cycles. I presented the findings to the full firm, and leadership adopted the expanded screen.

401(k) Fund Research

Built a Python model that ranked 401(k) plan fund options within each Morningstar category on 19 weighted metrics, including expense ratio, Sharpe ratio, alpha, downside capture, category-relative returns and manager tenure across 3- to 15-year horizons, for client plan due-diligence reviews.

Trading Operations

Managed daily trading operations for the firm's approximately $700 million book of business. Responsibilities included pre- and post-trade compliance checks, portfolio rebalancing across client accounts, wash sale rule monitoring, and execution of equity and fixed income trades through institutional platforms.

Portfolio Optimization

Conducted equity research and due diligence on alternative investments including private credit, real estate, venture capital, and private equity. Executed tax loss harvesting strategies across client portfolios to optimize after-tax returns while maintaining target asset allocations.

Independent Research

Leverage & Economic Cycles

An independent research paper investigating the relationship between corporate leverage and economic cycles. This work builds on research begun during my time at Vance Wealth, where I found statistical evidence that leveraged firms outperform in rising rate environments.

The study uses 30 years of fundamental data from the Terminal platform, overlaid with Federal Funds Rate data from FRED, to examine how capital structure decisions interact with monetary policy regimes. The goal is to produce a publishable analysis that contributes to the corporate finance literature on leverage and macroeconomic sensitivity.

Coming Soon

Background

Education & Certifications

Education

California State University, Northridge

Bachelor of Arts in Economics, Cum Laude

May 2024
GPA: 3.7  |  Minor: Finance
Dean's List, 6 semesters
Certificate of Excellence, Economics Department Chair
Vice President, Python Coding in Economics Club

Los Angeles Pierce College

Mathematics Coursework (non-degree)

2026 – Present
Completed Calculus I; Calculus II in progress
Planned: Calculus III, Differential Equations, Linear Algebra, Probability

Academic Projects

Economic Indicators' Impact on Automotive Sales

Investigated the relationship between macroeconomic indicators and U.S. automotive sales using OLS regression. Built automated data collection pipelines with Selenium and BeautifulSoup, implemented ARIMA time series forecasting, and conducted statistical analysis with statsmodels.

Machine Learning for Customer Retention Prediction

Developed a logistic regression model using scikit-learn to predict customer churn. Focused on feature engineering, model evaluation via F1-score optimization, and translating model outputs into actionable business recommendations.

Certifications

IBM

IBM Data Science Professional Certificate

IBM via Coursera

IBM

IBM Machine Learning Professional Certificate

IBM via Coursera

UM

Python for Everybody Specialization

University of Michigan via Coursera

K

Kaggle Certificates

Data analysis and machine learning tracks

Technical Skills

Languages
Python SQL JavaScript
Data & Analytics
DuckDB pandas scikit-learn statsmodels Plotly
Frameworks & Tools
Streamlit React Git Linux Selenium
Methods
OLS / Regression Time Series (ARIMA) Classification Backtesting

Overview

Resume

Founder & Managing Member, Explo Holdings

Jan 2026 – Present

Built a quantitative research platform covering 9,000+ companies and audited it for data errors. Write due-diligence research on public companies and maintain unit-level partnership accounting.

Investment Associate, Vance Wealth

Mar 2025 – Nov 2025

Trading operations for ~$700M book. Designed a direct indexing exclusion model (72 bps average outperformance) and presented the leverage findings to the full firm. Built a 401(k) fund scoring model. Equity research, tax loss harvesting, alternative investment due diligence.

B.A. Economics, Cum Laude, CSUN

May 2024

GPA 3.7, Finance minor, Dean's List (6 semesters), Certificate of Excellence. V.P. of Python Coding in Economics Club. Coursework in econometrics, business analytics, quantitative methods, and risk management.

Get in Touch

Contact

I am always open to conversations about economics, research, or economic consulting. Feel free to reach out through any of the channels below.